

Probability Theory: Mathematical Foundations and Applied Systems
Probability is a number between 0 and 1. Beyond that, there is no single answer. The classical interpretation, dominant before the twentieth century, assigns probability by symmetry: a fair six-sided die lands on any given face with probability 1/6. The frequentist interpretation defines probability as the limit of relative frequency over repeated trials, a coin’s probability of heads is the ratio observed as the number of tosses grows large. The Bayesian interpretation treats probability as a measure of belief, updated as evidence arrives. A Bayesian can assign a probability to the proposition that there was life on Mars a billion years ago; a frequentist cannot, because the event does not belong to a repeatable class.
The three interpretations answer different questions. Classical probability quantifies symmetry. Frequentist probability quantifies long-run frequency. Bayesian probability quantifies uncertainty given what is known. The disagreements are real, but so is the fact that all three converge on the same mathematical framework: Kolmogorov’s axioms of 1933, which treat probability as a measure on a sample space without committing to any single interpretation.
Interpretation | What it measures | What it cannot do |
|---|---|---|
Classical | Symmetry, all outcomes equally likely by structure | Handle asymmetric or real-world processes directly |
Frequentist | Long-run relative frequency over repeated trials | Assign probability to one-off or non-repeatable events |
Bayesian | Degree of belief, updated as evidence arrives | Provide an objective answer independent of the observer |
Sample Spaces, Events, and Distributions
A sample space is the set of all possible outcomes of a random experiment. An event is a subset of that space. Roll two dice: the sample space contains 36 ordered pairs. The event “sum equals 7” contains six of them. Probability is a function that assigns a number to each event, obeying three axioms: non-negativity, unit measure (the whole space gets 1), and countable additivity.
A probability distribution maps every outcome in the sample space to its probability. The mapping can be discrete, the binomial distribution counts successes in a fixed number of independent trials, or continuous, such as the normal distribution that describes everything from measurement errors to stock returns. The choice of distribution is never neutral. It encodes assumptions about the process generating the data, and when those assumptions fail, so does the model.
Law of Large Numbers and Convergence
The weak law of large numbers states that the sample mean converges in probability to the expected value as sample size grows. The strong law states that it converges almost surely, with probability one, the limit exists and equals the mean. The difference is technical but consequential. Weak convergence gives a probabilistic guarantee. Strong convergence says the long-run outcome is essentially deterministic.
The law is what connects probability models to observable reality. An insurance company does not need to know which policyholder will file a claim. It only needs the average claim frequency to be stable over a large pool. The same arithmetic governs a roulette wheel in a physical casino and the random number generator powering an online casino’s digital equivalent. The house edge, 2.7% on a European single-zero wheel, is a mathematical constant. The law of large numbers guarantees that over thousands of spins, the observed return converges to the theoretical expectation, regardless of short-term streaks.
Jacob Bernoulli proved the first version of the law of large numbers in his posthumous Ars Conjectandi (1713). He called it his “golden theorem” and laboured over it for twenty years. The proof was not published until eight years after his death.
Expected Value as a Decision Tool
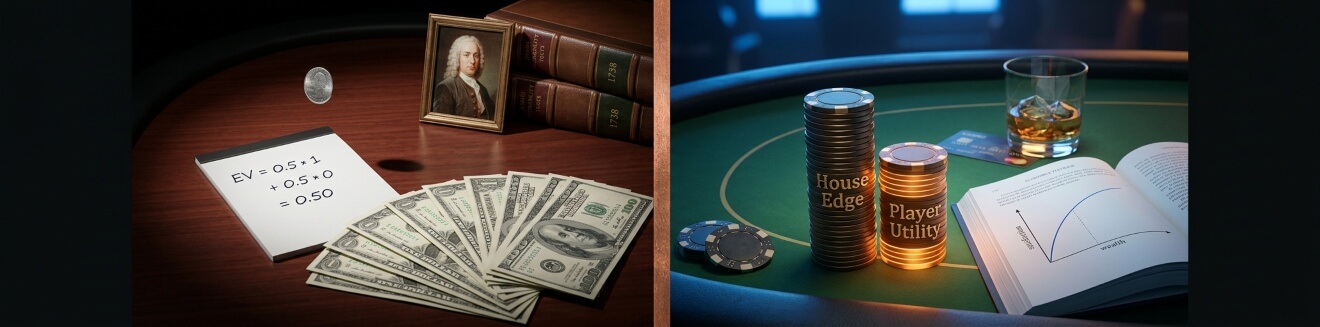
Expected value multiplies each outcome by its probability and sums the results. For a fair coin flip paying $1 on heads and $0 on tails, the expected value is $0.50. The arithmetic is simple. The interpretation is not.
Expected Monetary Value and the St. Petersburg Problem
Expected monetary value is the starting point for every formal treatment of decision under risk. But most individuals do not choose the option with the highest expected monetary value. Daniel Bernoulli identified the problem in 1738 with the St. Petersburg paradox: a game with infinite expected value that no rational person would pay more than a few dollars to play. The resolution was utility theory. People do not value money linearly. A dollar gained matters less than a dollar lost. Expected utility replaces monetary value with a function that reflects the decision-maker’s risk preferences.
Utility Theory and Risk Preferences
The distinction is visible in practice. An online casino player who continues betting after losing $100 is not necessarily irrational. The utility of the entertainment may offset the negative monetary expectation. The casino’s business model is built on the gap between expected value, negative for the player, positive for the house, and the utility the player derives from the experience.
Variance and Outcome Dispersion
Variance measures the spread of a distribution around its mean – the average squared deviation from expected value. Standard deviation, its square root, carries the same units as the original measurement and is more interpretable for that reason. A game with a high-variance payoff can generate dramatic short-term wins or losses even when its expected value is negative.
This is operationally important. A casino does not only design games with a house edge. It designs games whose variance keeps players engaged. A slot machine with a 95% return-to-player programmed into its lookup table can still produce a 200% return over fifty spins. The variance masks the negative expectation long enough to sustain play. The same probability structure, a negative drift disguised by high variance, appears in financial products that offer occasional large payouts in exchange for steady small losses. The mathematics is identical.
Finance, Insurance, and Online Casinos: One Probability Math
Three industries are built on probability. Finance uses it to price derivatives, model credit risk, and construct portfolios. Insurance pools independent risks so that the law of large numbers applies. Regulated gambling markets operate probability systems that are, unusually, fully auditable by participants. The mathematical structure is the same in all three; the transparency is not.
Finance and Derivative Pricing
Finance uses probability to price derivatives, model credit risk, and construct portfolios. The Black-Scholes equation, which won a Nobel Prize, is a probability model: it assumes stock returns follow a lognormal distribution and prices options accordingly. When the assumption fails, as it did in 1987 and 2008,. the model’s outputs diverge from market prices, sometimes catastrophically.
Insurance as a Pooled Risk System
Insurance pools independent risks so that the law of large numbers applies. Premiums are set to exceed expected claims by a margin that covers administrative costs and profit, exactly the same structure as a casino’s house edge. The difference is that insurance covers risks people would rather not face, while gambling creates risks people choose to take. The probability framework does not distinguish between these motivations.
Regulated Probability Systems
An online casino is the most transparent of the three as a probability system. The rules of a given game specify a sample space, a set of payoffs, and a randomisation mechanism. A player who understands the arithmetic knows the exact negative expectation before placing a bet. Regulated jurisdictions require that the random number generator powering such games be certified by an independent testing laboratory. The output is auditable; the probability distributions are published. No financial product offers that level of transparency. No insurance policy states its expected loss in advance. The mathematics that governs all three is the same; the accessibility of the model to the end user is not.
Where Mathematical Models Diverge from Reality
Probability models are closed systems. They assume known distributions, independent trials, and stable parameters. Reality does not comply. Financial markets exhibit tail dependence: extreme events occur together more often than independence predicts. Insurance claims are not independent in a pandemic. And even in the controlled environment of an online casino, a player does not experience a game as a sequence of independent Bernoulli trials. The human mind imposes patterns on randomness; the model does not.
The gap between model and reality is not a failure of probability theory. It is a property of any formal system applied to an open world. The theory tells you what follows from your assumptions. It does not tell you whether your assumptions hold. That judgment sits outside the mathematics, and it is where most practical error enters. Knowing the boundary is part of the discipline. The founding figures – Bernoulli, Laplace, Kolmogorov – all understood this. The model is a tool, not a prophecy.